The 2027 airfare forecasts disagree. Your travel budget still has to pick a number
Ryanair sees European fares up as much as 20%, GBTA sees 1.5%, and American posted record revenue with a loss. Budgeting for 2027.

If you are writing a corporate travel budget for 2027 this month, the industry has handed you two numbers for airfares, and they are not on speaking terms.
The first comes from the Global Business Travel Association, whose annual forecast, published in July with a travel management partner, expects average airfares to rise just 1.5% in 2027, after a 4.7% increase in 2026, according to The Business Travel Magazine. The second came last week from Michael O’Leary, the CEO of Ryanair, who told Euronews that European fares could rise by 10, 15, maybe 20% next year.
Somewhere in a finance department, a travel manager is being asked which of the two to put in the spreadsheet. I have some sympathy for that person, because the honest answer is “both, depending on where your people fly and when you asked.”
This piece is my attempt to explain why the forecasts diverge, what the latest airline results reveal about 2027 airfares, and how to build a budget that survives either scenario.
A disclosure before I start. I co-founded VOLL, a corporate travel and expense management platform in Latin America, so I spend a good part of every year looking at airfare data and talking to the people who pay for it. I also sit on the Tourism Council of FecomercioSP, the São Paulo trade federation, which means I get to read Brazilian airline economics up close. Both seats shape what follows.
Why the 2027 airfare forecasts disagree so much

The two numbers are less contradictory than they look, because they measure different things at different moments.
GBTA’s forecast is a global average across regions, cabins and routes, built in the middle of the year. It reflects a world in which demand for business travel keeps growing, capacity slowly recovers, and price increases flatten after two hot years. A global average is a useful instrument, and it also has the bad habit of hiding the extremes, which is exactly where travel budgets get hurt.
O’Leary is talking about short-haul Europe, after a sharp rise in fuel costs, and he is talking as someone who knows his own hedging book. Ryanair locked most of its 2026 fuel at a comfortable price, but he said the airline is roughly 85% unhedged for next year, and that most European carriers are in a similar position. He also expects fewer seats in 2027, as bankruptcies and consolidation thin out capacity, and he pointed to new aviation taxes, such as Belgium’s increase from €2 to €7 per passenger in January. The jet fuel price in Europe averaged around US$208 a barrel in mid-October, more than double the level of a year earlier, according to IATA figures cited in the same report.
Put simply, the forecast that was written before the fuel shock says “calm,” and the CEO who has to buy fuel next spring says “brace.” Both can be right at the same time, for different routes. A company whose people mostly fly domestic routes in Latin America has a different 2027 than one sending sales teams around Europe every week.
This is also why I keep coming back to a point I made when airfares hit a two-year high earlier this year: the average fare is a statistic, and nobody flies a statistic. Your budget lives on your routes, your advance purchase habits and your cabin mix.
What American Airlines’ record revenue and loss say about 2027 airfares
If you want a single document that explains the tension in airline pricing right now, read American Airlines’ third-quarter results, released on October 22 in an 8-K filing with the SEC.
The good news first. American reported record third-quarter revenue of US$16.3 billion, up 19.3% year over year. Unit revenue rose 14.5%. Premium revenue grew 22.9%. And the line that matters most for anyone in corporate travel: managed corporate revenue rose 27.6%, the sixth consecutive quarter of double-digit growth. Companies are flying, and they are flying in the front of the plane more often.
Then the bad news. Fuel averaged US$3.85 a gallon, up 62.7%, and fuel expense rose by US$1.9 billion. American posted a net loss for the quarter and now expects an adjusted loss for the full year 2026. For the fourth quarter, it projects revenue up roughly 20% and fuel at about US$4.70 a gallon, which is to say that the cost side keeps running ahead of the revenue side.
For a travel buyer, that combination has a clear implication. Demand is strong enough to support higher prices, and the airline’s cost base gives it every reason to charge them. Airlines rarely hold fares down when their own customers are booking more premium seats and corporate demand is growing at double digits. I wrote about the slim margins of this business in a piece on how little an airline makes on a ticket, and nothing in these results suggests carriers can absorb a fuel bill of this size indefinitely.
There is a nuance worth keeping. American is a U.S. carrier, with U.S. hedging choices and a U.S. corporate market. Still, the pattern of record revenue alongside losses is the clearest signal I know that fares have more room to rise than to fall, wherever fuel costs bite.
Brazilian airlines absorbed the fuel shock, for now
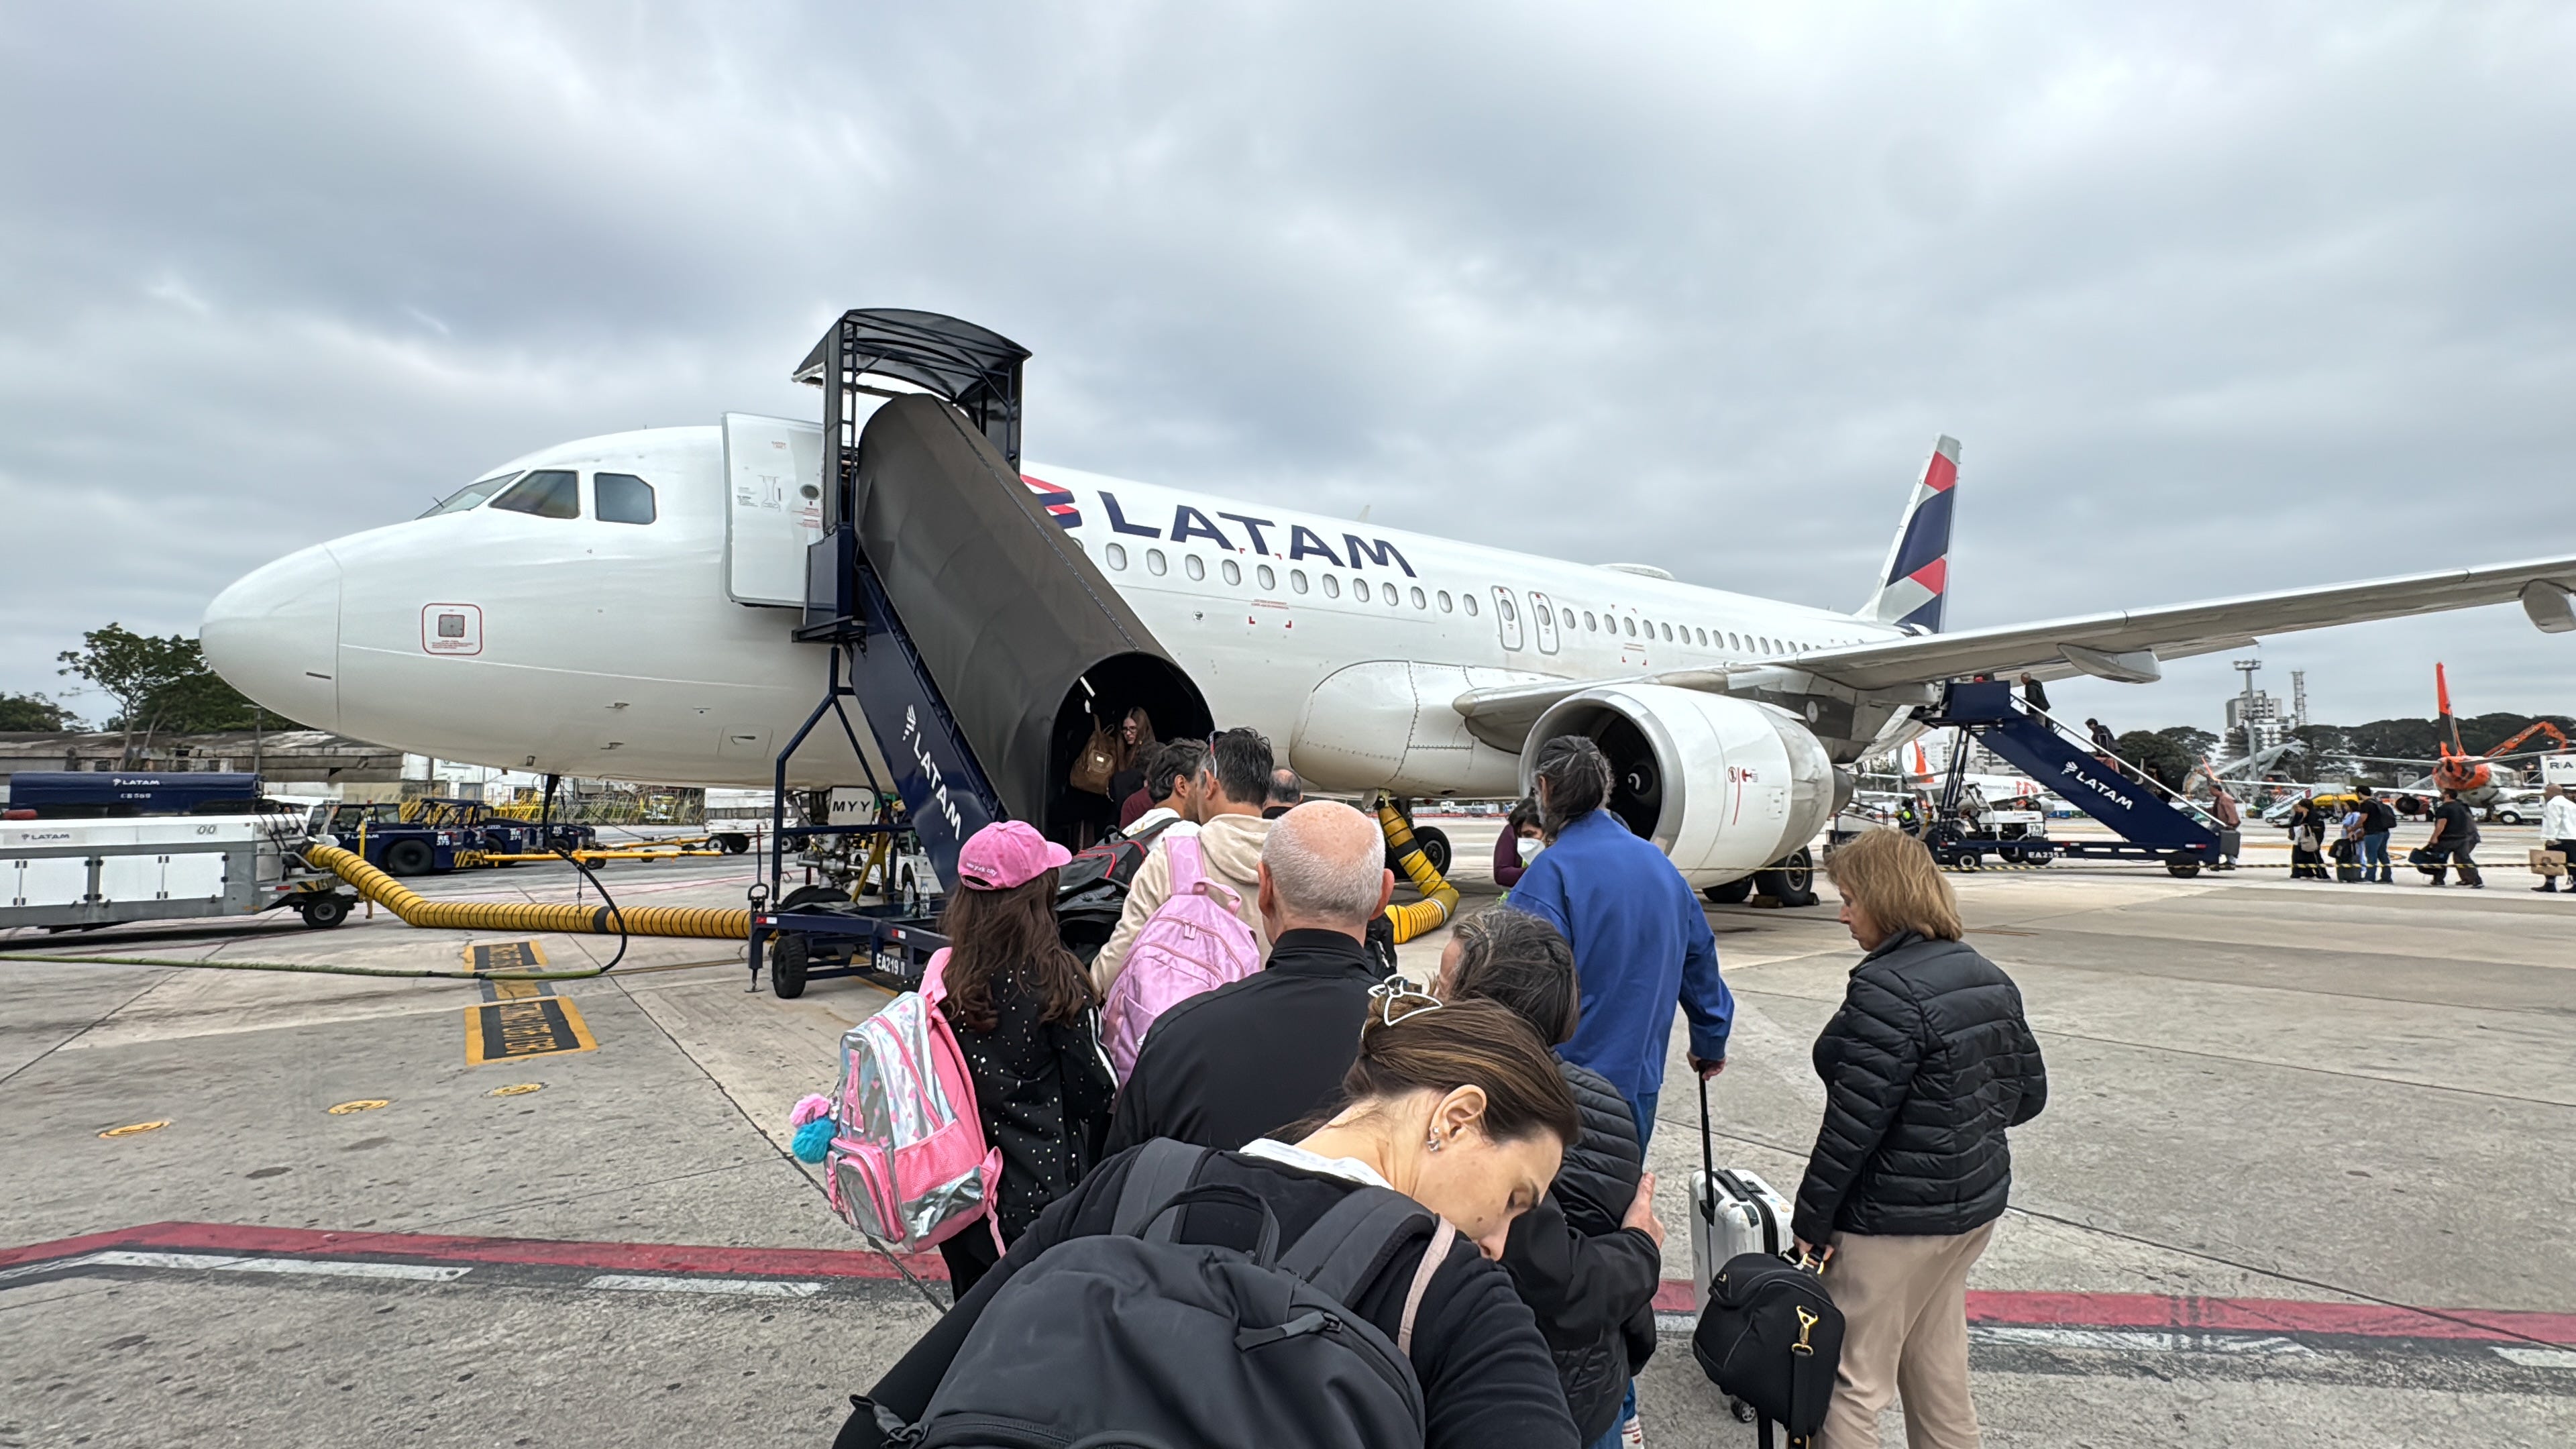
Here in Brazil, the story so far has been one of restraint, and it may not last.
My fellow council member at FecomercioSP, the economist Guilherme Dietze, published an analysis showing that jet fuel rose at least 37% between March and June compared with the same period of 2025, while domestic fares rose about 9%. By his calculation, full pass-through would have meant cost pressure of at least 12%. Brazilian airlines held prices below that line, helped by strong demand and a stronger real: passenger traffic grew 5.4% in the first half of the year, to 65.2 million, according to ANAC data cited in the analysis. His conclusion fits in one short line: higher costs without pass-through “vão pressionar as margens”, they will squeeze margins.
The global airline analysts at CAPA reached a compatible conclusion from a wider angle. In a recent Airline Leader briefing, they describe an industry moving from a problem of volume to a problem of the quality of growth, with 2027 shaping up as a year in which airlines pause expansion, retire older aircraft and cut marginal routes. Latin America stands out in the same briefing as one of the bright spots, with capacity up 3.8% and domestic growth in the region expected at 8% to 10% for the rest of the year.
That is good news for the region, and it carries a warning for budgets. Growth with squeezed margins tends to end in one of two ways: higher fares or fewer seats on the routes that make less money. For a Brazilian company with teams spread across secondary cities, the second option can cost more than the first. I wrote earlier this year that the Brazilian market is growing in price more than in volume, and 2027 looks set to test how long that can continue.
How Brazil’s tax reform could change airfares in 2027

Brazil adds a layer that no global forecast captures: the transition to a new consumption tax system, which starts in 2027.
A modeling study by ALTA, the Latin American and Caribbean air transport association, estimates that the reform could raise average domestic fares by 16.1% and international fares by 13.3%, as reported by Reforma Tributária. The calculation compares a current tax burden on air travel of roughly 9% with a reference rate of 26.5% under the new system, and it applies price elasticities specific to Brazil to project demand. The same study estimates a drop of about 21% in domestic demand if the full effect is passed through. IATA has taken the concern to the federal government and asked for a reduced rate or a postponement, according to Brasilturis.
Like every model, this one depends on assumptions, and the study itself says the actual effect will depend on how the reform is implemented. I treat it as a scenario, and an important one.
For corporate travel, there is a detail that changes the math. Under the new value-added system, companies buying tickets for business travel should be able to recover tax credits, while leisure travelers cannot, as LATAM Brasil’s CEO pointed out in the same Brasilturis report. The reform also eliminates the state tax on jet fuel, which lowers part of the airlines’ cost base. In other words, the sticker price of a corporate ticket may rise while its net cost to a company that manages its tax credits well rises less.
That turns a tax question into a process question. A company can only recover what it can document, which makes clean, consolidated travel data part of the finance team’s tax strategy from 2027 onward. If you want a refresher on what is already inside a ticket price, I broke it down in a piece on what an airline ticket actually pays for.
What corporate travel buyers say worries them about 2027

The people who manage travel programs are already feeling the shift. A survey of 204 corporate travel buyers by Business Travel Show America, reported by TravelDailyNews, found that airline costs are now the top concern for 2027, cited by 30% of buyers, double the 15% who said so a year earlier. Getting better value from suppliers was also cited by 30%, and improving policy compliance and reducing leakage by 29%.
I find the second and third answers more revealing than the first. When prices rise, the instinct of a mature travel program is to look inward: to negotiate harder, to bring stray bookings back into the program and to make sure the policy is actually followed. That is the right instinct. It also has limits, because a policy built for a calm year can generate more exceptions than savings in a turbulent one, a pattern I described when looking at how companies write policy when budgets rise.
The same survey shows technology as the fourth concern, cited by 28% of buyers, which says something about how many travel programs still run on tools that make reforecasting a manual exercise.
How to build a 2027 corporate travel budget when the forecasts disagree
So what goes in the spreadsheet? My practical answer is to stop looking for the right forecast and build a budget that works under more than one.
Start with your own routes. Separate domestic, regional and long-haul travel, and apply a different assumption to each. A company whose people fly mainly inside Brazil should think about fuel pass-through and the tax reform; one with heavy European travel should take O’Leary seriously; one with heavy U.S. travel should watch what American and its peers do with fares in the first quarter.
Write two scenarios. A base case anchored on GBTA’s moderate outlook, and a stress case that assumes meaningful fare increases on the routes you fly most. Agree in advance with finance what triggers a move from one to the other, so that in April the team is executing a plan everyone already agreed on.
Protect the advance purchase window. In a rising market, the cheapest seat on any route is usually the one bought early. A clear, enforced advance purchase rule is still the most reliable lever a travel manager controls, and in 2027 it may be worth more than any negotiated discount.
Look at the cabin policy with fresh eyes. American’s premium revenue is growing faster than its total revenue, and it is growing because companies are buying those seats. Decide deliberately which trips justify premium cabins, instead of letting the exception become the rule.
Bring finance into the tax conversation now. If tax credits on corporate tickets materialize as described, the companies that benefit will be the ones with clean, consolidated data on every trip. That work starts before January.
Reforecast every quarter. Fuel prices, hedging positions and tax rules will move during the year. A budget that is reviewed in April and July is a budget that can be defended in December.
None of this is glamorous, and I admit that “build two scenarios” is less exciting than a bold prediction. But a travel budget has one job, which is to let a company keep traveling to the meetings that matter without a crisis every time the price of fuel moves. In 2027, the companies that do this well will be the ones that treat airfare as a range to be managed, and plan their year around it.
As for the forecasts themselves, I suspect we will look back in twelve months and find that both were right somewhere. The trick is knowing in advance which “somewhere” is yours.
About me
I am an entrepreneur with over 20 years of experience at the intersection of tourism and technology. I am co-founder and Chief Business Officer of VOLL, the largest mobile-first corporate travel and expense management platform in Latin America, where I lead the commercial strategy behind our AI adoption.
A first-cohort graduate of The AI-Powered Organization at Stanford Graduate School of Business and a Marketing specialist from Fundação Dom Cabral, I serve on the Tourism Council of FecomércioSP and on the Executive Council of the Latin American Association of Corporate Events and Travel Management (Alagev). I write and speak about innovation, digital transformation, entrepreneurial leadership, and the future of corporate travel.
Discussion about this post